CLSA’s equity strategist outlines rationale for India upgrade
/ 3 min read
The shift from AI-focused markets, stability in the rupee as crude oil fell, and better-than-expected quarterly Q2FY27 earnings, were all positive factors.
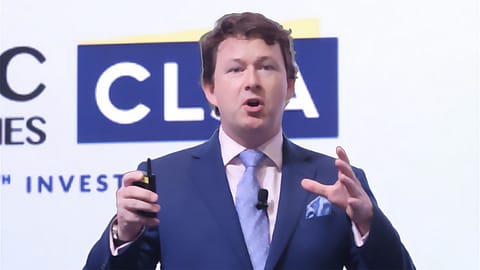
Alexander Redman, Chief Equity Strategist, CLSA. | Credits: LinkedIn @Alexander Redman
CLSA Chief Equity Strategist Alexander Redman was one of the earliest experts to upgrade India to an ‘overweight’ stance, in early November, just when foreign institutional investors stormed back into Indian equities by pumping in $8.4 billion in November, after being net sellers in India stock for 2025 and 2026 so far.
A slew of factors – the rotation of capital from AI-focussed markets of South Korea and Taiwan towards India; quarterly earnings starting to improve, stability of the Indian rupee as crude oil prices fell and India’s dollarized EPS climbing for the first time in two years – have all led to Redman having a rethink and a change in stance.
Investors have been buoyed by the return of FIIs into Indian qualities. The benchmark indices, Sensex index and the Nifty 50, have both risen over 9% in the past one month.
“Following $64 billion in net foreign selling, foreign ownership is at its lowest level since 2010, making India the third-largest underweight in dedicated emerging market funds. Even a pause in foreign selling allows strong domestic mutual fund and SIP inflows ($3.5 billion/month) to lift the market,” Redman told a select media briefing of CITIC Securities, owner of CLSA.
Redman said that the other encouraging thing is that private consumption growth will recover. “It was an inhibitor of GDP for the last few years, and as we go into next year, it will recover and become a leader again, thanks to a number of government initiatives, stimulus, tax cuts. which has got rural consumption picking back up again,” he said.
Add to this high credit growth of around 19.5% in October-end according to Reserve Bank of India data, which has been reflected by aggressive loan growth from Indian banks.
“When I look at India, you've got the beginnings of recovery from flat growth, earnings revisions have picked up, the market is lagging, GDP seems to confirm that EPS is appropriately positioned, and you've got a new driver in terms of private consumption growth resuming its leadership instead of being an inhibitor,” he added.
He reiterated that the stability of the rupee was a key factor in the changing of the foreign investor sentiment. “India is clearly one of the main beneficiaries of a peace dividend breaking out in the Middle-East,” he added.
Crude oil FOB prices for India has fallen to $96.19 per bbl in November from a high of $116 per bbl in September.
India’s ‘anti-AI trade’ label is turning to an asset from a liability. Investor antipathy towards Indian equities in the year to July 2026 mirrored that of US software and services, save the latter has bounced more convincingly than India,” a CLSA presentation made by Redman showed. Even before the AI boo, the weight of II Services in MSCI India fell to 15% from 26% on the way to 7%, the presentation showed.
On whether AI will be an opportunity or a challenge for India, Redman’s presentation showed that India’s large technology –services industry and expanding digital infrastructure provide a good foundation for AI adoption. AI could also lower the cost of providing education, healthcare and administrative services.
{{#most-powerful-women-snapshot-individual.slug}} {{/most-powerful-women-snapshot-individual.slug}} {{^most-powerful-women-snapshot-individual.slug}} {{/most-powerful-women-snapshot-individual.slug}} {{#showRanking}} {{current-rank}} {{/showRanking}} {{#photo.0.url}}
{{name}}
“Indian retail investors have been remarkably patient for the last couple of years. They have carried on allocating into this market for nothing, considering that the Nifty 50 index was flat. Let's hope the foreigners come back in and drive the index higher before the locals give up on the story,” he said.
Follow Fortune India
NEXT STORY