Fortune India Banking & NBFCs Summit 2026: Credit is growing faster than deposits, so how will banks fund India's next growth phase?
/ 2 min read
Bank of Maharashtra's Nidhu Saxena, IndusInd Bank's Rajiv Anand, HSBC India's Hitendra Dave and Karur Vysya Bank's B. Ramesh Babu discuss the widening gap between credit and deposit growth, shifting household savings patterns and the need for banks to explore alternative funding sources.
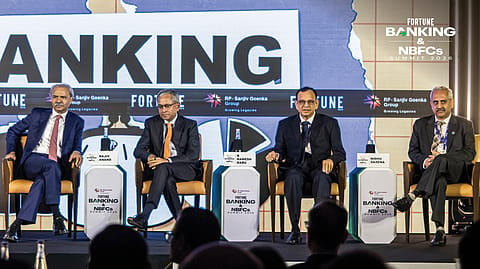
(L to R): Hitendra Dave, CEO, HSBC India; Rajiv Anand, MD & CEO, IndusInd Bank; B. Ramesh Babu, MD & CEO, Karur Vysya Bank; Nidhu Saxena, MD & CEO, Bank of Maharashtra
Indian banks are looking at alternative sources of funding as credit growth continues to outpace deposit growth, raising questions about how lenders will finance the next phase of expansion amid changing household savings patterns.
At the Fortune India Banking & NBFCs Summit 2026, Nidhu Saxena, managing director and chief executive officer of Bank of Maharashtra, flagged the widening gap between credit and deposit growth as a key concern, saying the industry could not continue relying solely on deposit mobilisation to support lending.
“How do we face this situation where credit is outpacing the deposit and continuously it is happening?” Saxena said during a panel discussion titled "Is this the Goldilocks moment for Indian banking?"
He pointed to a shift in household savings from bank deposits towards capital markets, with investors increasingly seeking higher returns. He also highlighted the funding requirements arising from India's infrastructure expansion, including new ports, airports and road connectivity.
“We just can't keep relying on mobilising deposits to support this kind of credit growth,” Saxena said.
Banks explore alternative funding
Saxena said lenders needed to explore other sources of capital to meet the economy's growing financing requirements. These could include raising debt or equity from domestic and overseas markets, alongside refinancing.
“I think that is going to replace the resources that we really need to become India, a developed nation where massive credit has to be extended by the banks,” he said.
Saxena added that investor interest in the banking sector remained strong. He said he had met around 200 domestic and foreign institutional investors individually and found significant interest in investing in Indian banks.
Rajiv Anand, managing director and CEO of IndusInd Bank, said lenders needed to rethink their liability mix rather than wait for household savings behaviour to change.
The shift towards digital payments and capital markets has changed how customers use their bank accounts, Anand said. At the same time, he pointed to stronger lending demand, with corporate banking growth reaching 16% and lending to micro, small and medium enterprises within the corporate book growing at more than 20%.
Deposit competition adds to pressure
Hitendra Dave, CEO of HSBC India, said banks also needed to address how deposit returns were compared with equity-market returns.
{{#most-powerful-women-snapshot-individual.slug}} {{/most-powerful-women-snapshot-individual.slug}} {{^most-powerful-women-snapshot-individual.slug}} {{/most-powerful-women-snapshot-individual.slug}} {{#showRanking}} {{current-rank}} {{/showRanking}} {{#photo.0.url}}
{{name}}
“As an industry, we have walked into that trap,” Dave said, referring to comparisons between equity returns and bank deposit rates despite the difference in risk.
He said HSBC had recorded compound annual growth of around 23-24% in savings accounts over the past three to four years, adding that the bank focused on customer relationships and differentiated propositions.
B. Ramesh Babu, managing director and CEO of Karur Vysya Bank, said lenders could look beyond the competition for low-cost current and savings account (CASA) deposits.
Banks could improve underwriting and selectively take additional credit risk within their risk appetite, particularly in retail and MSME lending, to help compensate for pressure on deposit costs, he added.
The discussion comes as banks contend with strong credit demand and relatively healthy asset quality, even as securing deposits becomes more challenging.
Follow Fortune India
NEXT STORY