Fortune India Banking & NBFCs Summit 2026: We handle 60 crore transactions every day, says SBI Chairman Setty
/ 3 min read
At the Fortune India Banking & NBFCs Summit 2026, SBI's investments in technology, particularly its digital banking platform YONO, have helped the bank expand its business without a proportional increase in physical infrastructure, he said.
THIS STORY FEATURES
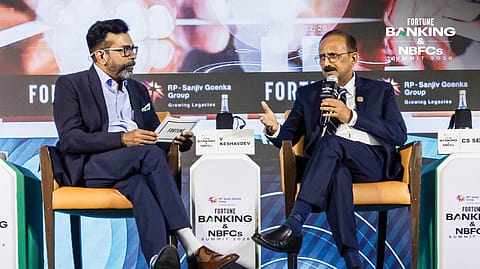
SBI Chairman C.S. Setty (right) with V. Keshavdev, Executive Editor, Fortune India, during a fireside chat at the Fortune India Banking & NBFCs Summit 2026 in Mumbai. | Credits: Fortune India
State Bank of India (SBI) has doubled its balance sheet since the consolidation of its associate banks without a corresponding increase in its branch network or employee strength, driven by investments in technology and digital banking, Chairman C.S. Setty said at the Fortune India Banking & NBFCs Summit 2026.
Speaking at a fireside chat titled Breaking into the Global Big League with V. Keshavdev, Executive Editor, Fortune India, Setty said SBI's digital transformation had enabled it to manage enormous transaction volumes while improving operating efficiency. “We handle 60 crore transactions every day, a volume that many banks may not process in an entire year,” Setty said, highlighting the scale at which India's largest lender operates.
SBI's investments in technology, particularly its digital banking platform YONO, have helped the bank expand its business without a proportional increase in physical infrastructure, he said.

Setty identified 2017, when SBI consolidated its five associate banks and Bharatiya Mahila Bank, as a turning point in its growth trajectory. Despite facing asset-quality challenges and reporting its first-ever annual loss in 2017-18, the bank continued to expand its balance sheet, doubling it by 2025.
The bank rationalised its branch network following the consolidation, while employee numbers did not increase significantly. Technology investments and the redesign of operational processes enabled SBI to handle rising business volumes more efficiently.
YONO key to reducing servicing costs
Setty said YONO's significance extended beyond being a mobile banking application, as it had transformed the way SBI delivered services and managed transactions. “We mobilise nearly a quarter of the nation’s savings, so reducing costs is a key priority for us. This is where digital transformation plays a crucial role.”
According to Setty, around 97-98% of SBI's transactions now take place outside bank branches, including those conducted through the Unified Payments Interface (UPI). Yet, the remaining branch-based transactions account for nearly 50 lakh customer visits daily, indicating considerable scope to migrate more customers to digital channels.
SBI has around 11 crore customers on YONO, with 2-3 crore customers logging in daily. Setty said expanding digital adoption would help the bank lower its cost of servicing customers and improve operating leverage. He also cited the platform's role in deposit mobilisation, noting that 74% of the bank's fixed deposits were booked through YONO. Customers can open deposits digitally, including through automatic transfers of surplus funds into fixed deposits.
Setty said SBI's transaction volumes underscored the importance of technology investments. The bank processes nearly 30 crore financial and non-financial UPI transactions daily, with a technical decline rate of just 0.01%, he said.
Deposit mobilisation faces structural shifts
The SBI chairperson acknowledged that Indian households were increasingly diversifying their savings across mutual funds, insurance, pension products, and other financial instruments, creating a structural shift in deposit mobilisation. “I think the structural shift which is happening in savings. This is structural. is irreversible, in my view.”
However, he said bank deposits would remain an important component of household savings as incomes grew and financial needs evolved. He added that digitalisation was changing competition within the banking sector, with customers increasingly choosing convenient channels to manage their money.
{{#most-powerful-women-snapshot-individual.slug}} {{/most-powerful-women-snapshot-individual.slug}} {{^most-powerful-women-snapshot-individual.slug}} {{/most-powerful-women-snapshot-individual.slug}} {{#showRanking}} {{current-rank}} {{/showRanking}} {{#photo.0.url}}
{{name}}
While banks must continue mobilising deposits, Setty said they also needed to explore alternative funding instruments to support credit growth. He expects the Indian banking system to remain predominantly deposit-led over the next five to six years.
Lending becomes more granular
On the lending side, Setty said banks were increasingly diversifying beyond large corporate loans towards retail borrowers and micro, small and medium enterprises (MSMEs). “The lending has become more granular... most of the banks have moved towards retail lending.”
The shift reflects lessons from the previous corporate bad-loan cycle, when banks faced significant asset-quality challenges. Improved digital infrastructure and the availability of more robust borrower data have also strengthened lenders' ability to expand retail and MSME credit, Setty said, adding that the changing composition of bank lending reflected broader economic trends, with granular credit gaining importance alongside corporate lending.
Follow Fortune India
NEXT STORY