India’s branded residences market expands to 45 projects across 18 cities
/ 2 min read
The commercial opportunity remains significant, with branded residences in India commanding a premium of around 25% to 40% over comparable unbranded properties, according to independent industry estimates.
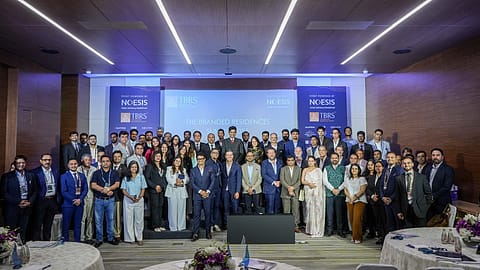
Day One of TBRS 2.0 will mark the launch of the third edition of the NOESIS Branded Residences Report.
India’s branded residences market is expanding beyond a handful of pioneering launches, with 45 projects now delivered or committed across 18 cities, according to the NOESIS Branded Residences India market map. Of these, only nine projects have been completed, while more than 20 others are at the early feasibility or brand-selection stage.
The next phase of the sector will be discussed at the second edition of The Branded Residences Summit (TBRS 2.0), curated by NOESIS Hotel Advisors, which will be held at JW Marriott Mumbai Sahar on October 7 and 8.
Branded homes command 25%-40% premium
The commercial opportunity remains significant, with branded residences in India commanding a premium of around 25% to 40% over comparable unbranded properties, according to independent industry estimates. However, the ability to capture that premium depends on decisions around feasibility, brand selection and deal structures, often made well before the first sale.
Delhi-NCR and Mumbai account for more than half of the projects tracked on the NOESIS market map, highlighting the concentration of the sector in the country's major real estate markets. The relatively limited presence across other cities could provide the next growth avenue for developers, investors and global hospitality brands.
“Nine delivered projects have shown India what it is capable of, and the next 36 will show the world. Everything that makes a branded residence endure is settled early, in the months before capital is committed,” said Nandivardhan Jain, curator of The Branded Residences Summit and founder and CEO of NOESIS Hotel Advisors.
Summit to focus on investment, execution and deal structures
Day One of TBRS 2.0 will mark the launch of the third edition of the NOESIS Branded Residences Report. Discussions will cover project feasibility, operator screening, the India market outlook, deal architecture and underwriting. A keynote will focus on the movement of India's private wealth and the growing appeal of branded residences.
The second day will focus on execution, including brand partnerships, hotel-led versus standalone models, sale-and-leaseback and assured-return structures, pre-launch sales, lifestyle brands and asset management after handover.
Speakers include Zubin Saxena of Hilton South Asia, Suma Venkatesh of IHCL, Gabriel Gn of Banyan Group, Kalpesh Mehta of Tribeca Developers, Daniel von Barloewen of Accor One Living, Jagdish Johal of YOO, and Fabio Calorio of Pininfarina. Around 20% of the faculty is expected to travel from Southeast Asia, Australia, the Middle East and Europe.
The summit will also feature a boardroom roundtable involving Motilal Oswal Alternates, HDFC Bank, ICICI Prudential, TCG Real Estate, and Certus, focusing on the category's investment potential and the opportunities emerging in the sector.
“We created TBRS because a category this young grows fastest when it learns together. A brand decision takes a few hours in a board meeting and thirty years to live with, and it deserves that much conversation,” Jain said.
NEXT STORY