
FSDC flags financial stability risks from AI boom, geopolitical uncertainty; FM Sitharaman seeks frequent meetings
ADVERTISEMENT
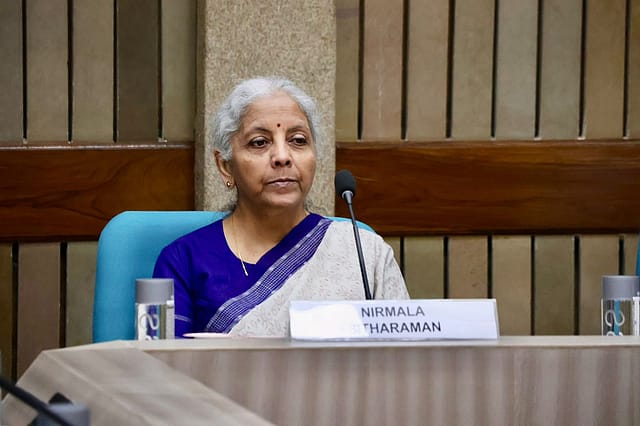
The Financial Stability and Development Council (FSDC), chaired by Finance Minister Nirmala Sitharaman, has called for heightened vigilance to safeguard India's financial stability amid geopolitical uncertainties, the artificial intelligence (AI) boom and a sharp rise in global bond yields.
At its 30th meeting in New Delhi on Friday, the council reviewed macro-financial stability and India's preparedness to deal with emerging risks. Sitharaman also urged the council to meet more frequently, with a predefined schedule, citing rising geopolitical headwinds and global uncertainty.
The Finance Ministry said the FSDC stressed the “need to be vigilant especially in view of the ongoing geopolitical uncertainties, AI boom and steep rise in global bond yields”.
The council also recognised the need for “proactive efforts to mitigate potential risks to financial stability” while adopting safeguards to strengthen the resilience of the financial system.
Cybersecurity and tokenisation on agenda
The FSDC discussed measures to promote innovation in financial technology and explored the prospects of tokenisation of financial assets and other real-world assets.
It also reviewed cybersecurity preparedness across the financial sector and took note of the Financial Sector Cyber Security Strategy formulated by an inter-ministerial group comprising financial regulators and cybersecurity agencies, in coordination with the Department of Economic Affairs, Department of Financial Services and Ministry of Electronics and Information Technology.
The strategy is expected to strengthen the financial sector's overall cyber resilience. Discussions also covered the protection of critical information infrastructure and cybersecurity preparedness at regional rural banks.
Focus on investment, KYC reforms and MSME credit
The council reviewed measures to strengthen the domestic investment ecosystem and improve the flow of resources for investment, including through GIFT International Financial Services Centre (GIFT-IFSC).
Other areas discussed included simplifying and digitising know-your-customer (KYC) processes and digital onboarding for non-resident Indians and foreign portfolio investors.
The FSDC also considered reforms to scale up India's digital public infrastructure, including the Account Aggregator framework and the Unified Lending Interface (ULI), with a specific focus on micro, small and medium enterprises (MSMEs).
Reducing financial-sector intermediation costs, improving regulatory responsiveness and rationalising credit guarantee schemes were also on the agenda.
Push to return unclaimed financial assets
Sitharaman urged regulators and other stakeholders to expedite refunds of unclaimed financial assets, including bank deposits, dividends, shares, post office accounts, insurance and pension funds, to their rightful owners.
The council took note of the progress made under the government's “Your Money, Your Right” campaign, which seeks to return unclaimed assets through district-level initiatives. It asked ministries and regulators to continue efforts to ensure timely refunds.
The Finance Ministry said Sitharaman had urged the council to meet “at more frequent intervals with a predefined schedule” in view of rising geopolitical headwinds and global uncertainty.
The meeting was attended by Reserve Bank of India Governor Sanjay Malhotra, Securities and Exchange Board of India chairperson Tuhin Kanta Pandey, Insurance Regulatory and Development Authority of India Chairperson Ajay Seth and other senior officials and financial-sector regulators.