
NSE IPO listing: Shares gain 5% after flat debut; brokerages see further upside
ADVERTISEMENT
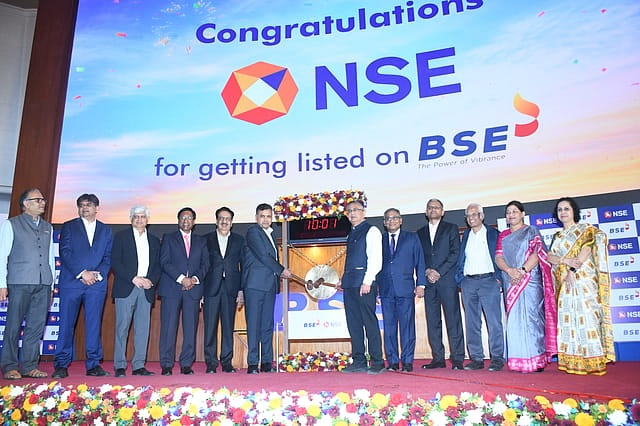
Shares of the National Stock Exchange of India (NSE) rose over 5% in the first hour of trade on Thursday, after making a muted debut on the Bombay Stock Exchange.
The NSE shares climbed 5.2% to ₹1,878, against its initial public offering (IPO) price of ₹1,785, with around 3.85 crore shares changing hands over the counter. At the time of reporting, NSE share price was at ₹1,843, up 3.25%, with a market capitalisation of about ₹4.57 lakh crore.
Early today, NSE shares debuted at ₹1,800, a 0.84% premium to its issue price, valuing the exchange at around ₹4.45 lakh crore. The listing was below grey-market expectations, with the pre-listing premium of ₹40 indicating an expected debut of around ₹1,825, or a 2.24% premium.
Brokerages flag growth opportunity, regulatory risks
Brokerages remain positive on NSE's dominant position, strong cash generation and India's financialisation story, but have flagged its dependence on trading volumes and regulatory changes as key risks.
Shivani Nyati, Head of Wealth at Swastika Investmart, said NSE's modest listing premium reflected realistic market expectations. She highlighted its approximately 93% share of the cash segment and 99.8% share in equity futures.
Nyati noted that NSE's issue-price valuation of 40.9-42.9 times FY26 diluted earnings was below BSE's roughly 54.3 times. However, nearly 79% of NSE's revenue is linked to trading activity, leaving earnings sensitive to market volumes and regulatory changes.
She said NSE's "unmatched, near-monopolistic position in the Indian capital markets" provides it with a strong competitive moat, while cautioning that its earnings remain sensitive to market activity cycles and regulatory shifts.
Emkay sees 15% upside
Emkay Global initiated coverage on NSE with a BUY rating and a September 2027 target price of ₹2,050, implying about 15% upside from the ₹1,785 issue price.
The brokerage expects NSE to deliver around 13% EPS CAGR in FY27-29, following approximately 19% growth in FY22-26. Revenue is estimated to grow at around 12% annually, while EBITDA and PAT are expected to grow at roughly 13%.
Emkay cited NSE's dominant market position, India's financialisation opportunity and strong profitability and cash generation as key drivers. It expects rising household savings, SIP flows and capital formation to support market growth.
"Given its strong brand, dominant leadership position, profitability, and cash generation, we see a strong case for NSE shares to be part of every India-focused equity portfolio," Emkay said.
PL Capital sees slower growth
PL Capital initiated coverage with an Accumulate rating and a target price of ₹1,950, valuing NSE at 35 times FY29 earnings.
The brokerage flagged the decline in NSE's index-options market share as a key drag. Its share fell from around 97% in FY24 to 72% in FY26 and 65% in YTDFY27, amid regulatory changes including restrictions on weekly expiries, the Closing Auction Session and prop-trading rules.
PL Capital expects NSE's revenue and PAT to grow at around 11% CAGR over FY26-29, versus 25% revenue growth during FY21-26.
Transaction income accounted for 79% of operating revenue in FY26. The brokerage expects transaction income to grow at around 9% annually, while non-transaction businesses such as listing services, colocation, data feeds and index licensing are expected to grow at around 14%.
PL Capital expects EBITDA margins to recover to 76% by FY29, from 71.3% in FY26, while PAT is projected to grow at around 11% annually.
"Market dominance in cash and futures to continue; share erosion in index options to be a drag," PL Capital said, highlighting the key growth-versus-regulation trade-off for NSE.
Lower trading volumes caused by regulatory changes or market volatility remain key risks. PL Capital's sensitivity analysis suggests such factors could affect FY27 and FY28 PAT by around 6.4% and 6.3%, respectively.