
Mid- and small-caps have stronger earnings momentum, but valuations matter: Motilal Oswal’s Anupam Guha
ADVERTISEMENT
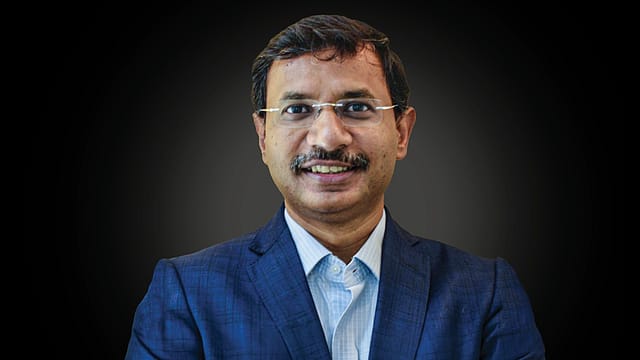
India’s mid- and small-cap companies are outpacing their large-cap peers in earnings growth, supported by emerging opportunities in manufacturing, defence, electronics, and data centres. However, elevated valuations in parts of the market and persistent foreign investor selling make selective stock picking critical, according to Anupam Guha, MD & CEO of Motilal Oswal Private Wealth.
In an exclusive interview with Fortune India, Guha said the shift in earnings momentum towards smaller companies was creating investment opportunities but cautioned against treating the rally as a broad-based buying opportunity. Investors need to assess whether companies can convert order books and growth plans into sustainable revenues, cash flows, and returns.
In Q1FY27, mid-cap profits grew 23% year-on-year while small-cap profits rose 31%, compared with 18% growth for Nifty 50 companies. The earnings momentum is expected to continue in the September quarter, although valuations remain a key consideration.
Earnings growth broadens beyond largecaps
Manufacturing, electronics, defence, capital goods, data centres, and new-age businesses are opening up growth opportunities, particularly among mid- and small-cap companies. Consistent inflows into mid- and small-cap mutual funds have also supported their performance. However, Guha said investors should focus on businesses that are scaling up, gaining market share and converting growth into cash flows rather than buying stocks solely based on their market capitalisation.
Motilal Oswal Research expects Nifty 50 earnings to grow 27% year-on-year in Q2FY27, the strongest growth in 17 quarters. Its coverage of large-, mid- and small-cap companies is expected to report earnings growth of 23%, 11% and 29%, respectively.
The key test for smaller companies will be whether order books and management guidance translate into revenue growth and improved returns. Companies whose valuations already factor in strong future earnings could face a sharp correction if performance disappoints.
Largecaps offer a valuation opportunity
Persistent foreign institutional investor (FII) selling has weighed on large-cap stocks, while global capital has been concentrated in artificial intelligence and semiconductor-led opportunities. Domestic institutional investors have helped absorb some of the selling pressure.
Calendar-year FII outflows have exceeded $30 billion, putting pressure on index heavyweights, particularly in financials and information technology.
At the end of September 2026, the Nifty 50 traded at around 17.2 times one-year forward earnings, about 18% below its long-period average of 20.9 times. In comparison, the Nifty Midcap 150 traded at 22.8 times forward earnings and the Nifty Smallcap 250 at 23.2 times. While midcaps were only modestly below their historical average, smallcaps continued to trade at a premium. The correction has improved valuations across parts of the market, but not uniformly.
Guha said investors should assess both absolute and relative valuations. Companies with superior earnings growth, high return ratios and durable competitive advantages can command a premium, but stocks priced for years of uninterrupted growth leave little room for earnings disappointment.
IPO boom must translate into productive investment
According to Guha, record initial public offering (IPO) fundraising reflects companies’ willingness to raise capital for expansion and investors’ appetite for new listed businesses. Proceeds can fund capacity expansion, new business lines, deleveraging, and greater institutionalisation. However, the quality of businesses entering the market and their post-listing performance will determine whether the IPO boom creates lasting value. Heavy issuance can also absorb liquidity from the secondary market.
Investors must distinguish between companies raising money to finance productive growth and offerings primarily facilitating promoter exits, Guha said.
Rising mergers and acquisitions (M&A) activity also needs to be assessed on the basis of strategic intent rather than deal volumes alone. Acquisitions that help established companies access technology, digital capabilities, distribution networks or new customers can create new revenue streams and profit pools. By contrast, acquisitions driven by weak internal growth may be defensive. Investors should examine the quality of acquired businesses, integration risks, deal sizes relative to capital expenditure and returns on capital.
Foreign inflows could support emerging sectors
A reversal in foreign capital flows could benefit under-owned, high-growth segments such as private defence, aerospace, data centres, electronics, electric vehicles, and digital platforms. However, foreign investors are likely to look for strong earnings growth, reasonable valuations, currency stability and compelling long-term growth prospects before increasing their exposure to Indian equities. High energy prices, geopolitical uncertainty, and elevated bond yields remain potential headwinds, he noted.
For investors navigating a market in which benchmark indices have remained range-bound even as some companies outside the indices delivered double-digit earnings growth, the distinction between price weakness and deteriorating fundamentals is crucial.
Lower share prices can improve prospective returns when earnings remain resilient. Where earnings weakness is structural, however, investors should avoid trying to catch falling stocks and instead look for companies offering sustainable growth at reasonable valuations.
Earnings and valuations will determine market leadership
Guha said a lasting shift in market leadership cannot be established by price performance alone. Stronger earnings growth, improving return ratios, positive earnings revisions and sustained institutional flows are important indicators that a new set of market leaders is emerging.
Market breadth also matters. A rally concentrated in a handful of stocks is less convincing than one that spreads across sectors and persists for several quarters.
Interest rates, liquidity, commodity prices, and currency movements can further influence sector performance and investor appetite, he said while adding that a structural shift becomes more credible when earnings, valuations, price performance and capital flows reinforce one another. Until then, investors need to distinguish between a durable change in market leadership and a temporary rotation into mid- and small-cap stocks, Guha said.