NSE shares slip below IPO price; down over 6% from listing-day high
/ 2 min read
NSE shares fell to a new low of ₹1,761 on the BSE today, down more than 6% from their listing-day high of ₹1,878.
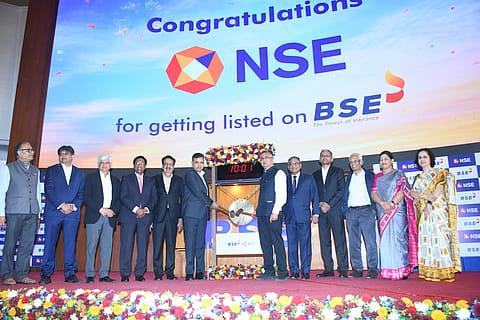
NSE shares got listed on the BSE on Sept 24 | Credits: NSE
Shares of the newly listed National Stock Exchange of India slipped below their initial public offering (IPO) price on Monday, falling nearly 2% in intraday trade.
NSE shares opened a tad lower at ₹1,786 on the BSE, against the previous close of ₹1,792.65. Extending their losses, the stock declined as much as 1.76% to hit a new low of ₹1,761, taking its market capitalisation to ₹4.37 lakh crore. The stock is now down more than 6% from its listing-day high of ₹1,878.
NSE debuted on the BSE on September 24 at ₹1,800, a 0.84% premium to its issue price of ₹1,785, valuing the exchange at around ₹4.45 lakh crore. The stock gained as much as 5.2% on the listing day to hit ₹1,878 before giving up most of those gains.
Brokerages remain positive despite near-term pressure
Santosh Meena, Head of Research at Swastika Investmart, attributed the recent decline to a broader market sell-off triggered by rising crude oil prices and escalating geopolitical tensions, profit-booking after a muted listing, and valuation sensitivity at around 43 times FY26 earnings. The pure offer-for-sale structure and limited retail participation have also weighed on sentiment, he said.
In the near term, the stock is likely to remain volatile and track overall market direction and trading volumes, Meena said. He added that NSE’s dominant market share, high margins, strong cash generation and structural benefits from India’s financialisation support the longer-term outlook.
Post listing, Emkay Global initiated coverage on NSE with a BUY rating and a September 2027 target price of ₹2,050, implying around 15% upside from the ₹1,785 issue price.
The brokerage expects NSE to deliver around 13% EPS CAGR in FY27–29, following approximately 19% growth in FY22–26. Revenue is estimated to grow at around 12% annually, while EBITDA and PAT are expected to grow at roughly 13%.
PL Capital also initiated coverage with an ‘Accumulate’ rating and a target price of ₹1,950, valuing NSE at 35 times FY29 earnings.
The brokerage flagged the decline in NSE’s index-options market share as a key drag. Its share fell from around 97% in FY24 to 72% in FY26 and 65% in YTD FY27, amid regulatory changes including restrictions on weekly expiries, the Closing Auction Session and proprietary trading rules.
PL Capital expects NSE’s revenue and PAT to grow at around 11% CAGR over FY26–29, compared with 25% revenue growth during FY21–26.
NEXT STORY