
Geopolitics, crude, and global yields may push 10-year G-sec yield beyond 7.25%: DSP MF’s Sandeep Yadav
ADVERTISEMENT
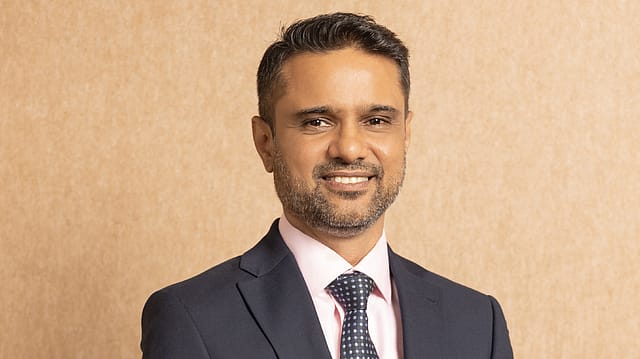
The sharp rise in government bond yields is being driven more by geopolitical risks, currency concerns, and global yields than by domestic inflation and growth, says Sandeep Yadav, Executive Director and Head of Fixed Income at DSP Mutual Fund. In an exclusive interview with Fortune India, Yadav says the 10-year G-sec yield could move beyond the 7.25% level if the Iran war continues while sustained crude prices above $108 a barrel could add to inflation, the current account deficit, and fiscal pressures.
Global risks are driving the bond selloff
The sharp rise in the 10-year government security yield has come amid growing concerns over the rupee and geopolitical tensions. According to Yadav, these factors have fuelled expectations of a possible rate hike by the Reserve Bank of India (RBI), in line with the tightening expectations surrounding other major central banks.
The negative sentiment has also been amplified by the RBI’s sale of government securities through open market operations, aimed at absorbing the rupee liquidity generated by foreign-currency non-resident (FCNR) flows.
“The domestic inflation and growth has not changed so drastically to merit such spike in rates. Thus, the biggest worry remains the global factors and their impact on FX inflows in India,” Yadav says.
With the 10-year G-sec yield approaching the 7.25% mark, the level could become an important reference point for the market. However, Yadav cautions that it may not provide a durable floor if the Iran conflict persists. “If the Iran war continues, 7.25% may not remain a support for too long,” he says, adding that higher global yields could continue to exert pressure on Indian government securities.
Crude above $108 could complicate the inflation outlook
A sustained rise in crude oil prices presents another significant risk for the bond market. With crude already above $108 a barrel, Yadav expects prolonged elevated prices to feed into inflation, widen the current account deficit (CAD) and put additional pressure on the rupee.
The government has so far absorbed part of the impact of higher oil prices through tax reductions. But Yadav says maintaining such support could become increasingly difficult as it would put pressure on the fiscal deficit and potentially require higher government borrowing.
If the government withdraws some of that support, the inflationary impact of expensive crude could become more visible. “Thus, one can expect much higher inflation if oil sustains higher—and further rate hikes in months to come,” he says.
RBI bond sales add to market pressure
The RBI’s government securities sales have become another source of concern for investors, particularly in a market already grappling with weak sentiment.
According to Yadav, the impact of the RBI’s bond-sale programme needs to be viewed in the context of current market conditions. While a sale of shorter-duration government securities may not ordinarily trigger a major reaction, the same action can have a much larger impact when investors are already worried about currency movements, global yields and geopolitical risks.
“In such a scenario the RBI's G-sec sale has accentuated the fears,” he says. “The bond sale has and should lead to even higher yields.”
US yields may not change foreign investor behaviour dramatically
Higher US Treasury yields are another factor putting pressure on global bond markets. However, Yadav does not expect the rise in US yields alone to significantly alter foreign investors’ approach to Indian government securities.
Foreign investor demand for Indian government bonds has remained relatively limited for several years, he says. Much of the meaningful inflow in recent years has come through passive investments following India’s inclusion in global bond indices. “There have been tactical inflows and outflows as those investors look for quick capital gains—but long-term investors are few,” Yadav says.
As a result, higher US yields may not materially change the underlying foreign-investor interest in Indian government securities. This is also reflected in the relatively modest, but still positive, foreign inflows into Indian bonds this year, despite the rise in US yields.
Longer-duration bonds face greater absorption risk
The government’s increased reliance on longer-tenor securities is also creating challenges for the bond market. Issuance of 15-, 30- and 40-year government securities has raised concerns about the market’s ability to absorb duration. Yadav points to the widening spread between 10-year and 40-year government bonds as evidence of the pressure facing the longer end of the yield curve.
“Markets were facing issues in absorbing the longer-term borrowing—as evidenced in high spreads between 10-year and 40-year bonds. The higher issuances will keep the pressure elevated,” he says.
Short-duration bonds offer a way to manage uncertainty
For bond investors, Yadav believes the current environment calls for greater caution on duration. Longer-term yields have a stronger linkage with geopolitical developments, which remain difficult to predict.
Short-term securities, by contrast, tend to carry lower volatility and lower duration risk. Even if a global shock results in a sharp movement in yields, the shorter maturity reduces the extent of interest-rate risk for investors. “In current times, with geopolitics risk difficult to predict it is better for investors to be placed in short-term risk,” Yadav says.
That does not mean investors should permanently avoid longer-duration bonds. If geopolitical tensions ease, the market could offer opportunities to extend duration, he says, allowing investors to lock into yields at more favourable levels.
RBI liquidity moves key signal ahead of October MPC
Going into the October monetary policy meeting, Yadav says investors should closely monitor the RBI’s liquidity-absorption announcements. These could offer clues about the central bank’s assessment of liquidity conditions and its broader policy stance.
There are relatively few major domestic data points between now and the policy meeting that could materially alter the RBI’s current assessment, he says. “Thus, looking at current parameters, it seems RBI will hike the rates,” Yadav says while adding that any positive surprise on the Iran war could alter those expectations.
For the bond market, therefore, the immediate question is not simply where domestic inflation or growth is headed. The bigger uncertainty lies in how long the geopolitical shock lasts, how high crude prices climb, and how those developments feed into the rupee, foreign capital flows and the RBI’s policy response.