
Financial inclusion must go beyond bank accounts to credit, insurance, and pensions: Maharashtra Governor
ADVERTISEMENT
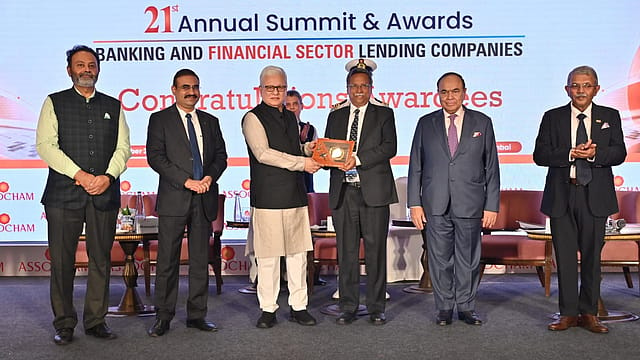
Financial inclusion must extend beyond opening bank accounts and enabling digital payments to ensure access to affordable credit, insurance and pension coverage, particularly for rural households, women and small entrepreneurs, Maharashtra Governor Jishnu Dev Varma said on Friday.
Addressing the 21st Annual Summit & Awards of the ASSOCHAM National Council for Banking and Financial Sector Lending Companies in Mumbai, Varma said financial institutions must ensure that technology-driven banking translates into wider access to financial services and opportunities across society.
“Banks and financial institutions are not merely providers of loans and financial services; they are partners in nation-building,” Varma said. He stressed the need for a financial system that is stable, innovative and inclusive, with credit flowing to productive sectors and technology serving people's needs.
Held under the theme Resilience, Reinvention and India’s Rise, the summit brought together policymakers, banking leaders and industry stakeholders to discuss financial inclusion, specialised lending, digital transformation and responsible innovation.
Banks must support India’s $30 trillion economy ambition
Atul Kumar Goel, chief executive of the Indian Banks Association, said the banking and financial services sector would be instrumental in achieving India's ambition of becoming a $30 trillion economy by 2047.
“India’s banking and financial services sector can be the catalyst for achieving the vision of a $30 trillion economy by 2047,” Goel said, identifying productivity, digital maturity, growth and resilience as key priorities.
He said financing for emerging sectors such as renewable energy, semiconductors and micro, small and medium enterprises (MSMEs) would be critical to sustaining economic growth. Greater use of artificial intelligence to improve operational efficiency, stronger digital public infrastructure and cybersecurity across financial products would also be important, he added.
Responsible lending and governance remain critical
ASSOCHAM President Nirmal K. Minda highlighted the need to balance financial innovation with strong governance, transparency and responsible lending.
India’s banking and financial sector has demonstrated resilience and adaptability over the past decade, Minda said, adding that financial institutions would play a crucial role in financing infrastructure, manufacturing, housing, agriculture, MSMEs and emerging enterprises as the country moves towards becoming a developed economy.
He said digitisation, fintech and artificial intelligence were transforming financial services, making trust, cybersecurity, transparency and robust governance essential to building a reliable financial system.
₹30 trillion MSME credit gap needs attention
Manish Jain, co-chairman of the ASSOCHAM National Council for Banking and executive director of YES Bank, called for stronger specialised lending capabilities to support emerging industries and improve credit access for small businesses.
He said banks must build industry expertise to finance sectors such as green hydrogen, semiconductors, space technology and electric mobility, alongside infrastructure and the energy transition. “Bridging the ₹30 trillion MSME credit gap through advanced digital underwriting, ecosystem-driven financing models and greater integration of small businesses into global value chains will be vital to advancing inclusive growth,” Jain said.
ASSOCHAM-EY report released at summit
The summit also saw the release of the ASSOCHAM-EY Knowledge Report, which contributed to discussions on the priorities and opportunities shaping the banking and financial services industry.
A special session honoured awardees from the banking and financial sector lending industry for their contributions to the sector.
Concluding the summit, ASSOCHAM secretary general Saurabh Sanyal emphasised the importance of collaboration among the government, regulators and industry in strengthening India's financial ecosystem.
He said banks, non-banking financial companies (NBFCs), fintech firms and other financial institutions would play an increasingly important role in driving economic growth and financial inclusion. He added that platforms such as the summit could help stakeholders address emerging challenges and develop a roadmap for a stronger, more inclusive and future-ready financial sector.