
India’s AC, fridge and washing machine markets have room to double, but costs remain a hurdle: Voltas MD
ADVERTISEMENT
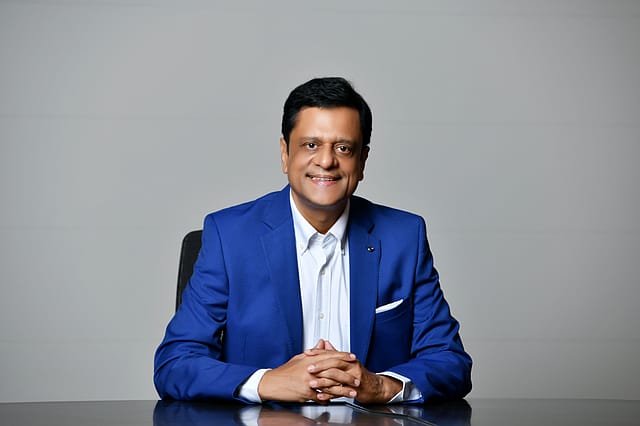
India’s consumer durables industry is staring at a significant growth opportunity as penetration of air conditioners, refrigerators and washing machines remains well below levels seen in comparable economies, but closing the cost gap with China and reducing dependence on imported components will be critical to unlocking that potential, said Mukundan Menon, chairman, CII National Committee on Consumer Electronics & Durables and managing director of Voltas Ltd .
Speaking at the Consumer Electronics & Durables Summit 2026, Menon said India’s relatively low household penetration across the three categories, coupled with its current per-capita GDP of around $3,000, leaves substantial room for domestic demand to expand.
“We are currently at a very important point in this industry, which is the consumer electronics and the durable industry,” Menon said.
Air conditioner penetration in India is currently below 10%, while washing machines are below 20% and refrigerators below 35%. He said that when India is compared with countries at a similar stage of economic development, the gap becomes even more apparent.
“There’s a huge headroom for growth,” he said, pointing particularly to rural and semi-urban India, where lower household penetration remains a major opportunity.
The industry is now looking at taking AC penetration from below 10% to around 20% over the next few years, washing machines from below 20% to 30%, and refrigerators to around 50%.
India wants to move beyond assembly
While rising domestic demand could provide a major growth engine, Menon said the larger opportunity lies in combining consumption growth with exports and deeper localisation of the manufacturing ecosystem.
India currently accounts for less than 0.6% of global air conditioner exports, compared with around 50-60% for China, 14-15% for Thailand and more than 10% for Vietnam, he said.
“I see no reason why India cannot be at least a double-digit player in the exports market,” Menon said.
However, competitiveness remains a challenge. India currently has a cost disadvantage of roughly 15-16% compared with China. Recent free trade agreements could help narrow that gap, with the proposed India-European Union FTA alone potentially providing a 2.5% cost advantage, bringing the gap down to around 12.5%, he said.
The government’s production-linked incentive scheme has also played an important role in building domestic manufacturing capacity, particularly in sub-assemblies and components. Menon said the focus of the PLI scheme was deliberately placed beyond finished-goods assembly so that India could develop a wider manufacturing ecosystem.
“The government was very clear that India should not become just an assembly place. It should become a sub-component manufacturing hub,” he said.
That localisation push remains one of the three key priorities for the industry. Several categories currently have an imported component share of around 30-35%, and the industry wants to eventually bring this down to zero.
In all, Menon said the industry’s discussions would centre around three priorities: expanding domestic demand, capturing the export opportunity and making the component ecosystem fully India-based.
The broader objective, he said, is to move India from a market with relatively low penetration and significant import dependence to a manufacturing base that can serve both domestic consumers and global markets.